The natural gas shortage is moving to Japan.
- List of Correlations
- Gold Checklist
- Copper Checklist
- Gold Forecaster
- Oil Forecaster
- Stock Forecaster
- Bond Forecaster
- USD Forecaster
- Poo Forecaster
- Bitcoin Checklist
- Q Ratio
- Stock Valuation
- Leading/Coincident Indicator
- Misery Index
- Junk Bonds Vs. Stocks
- Currency Vs. Bonds
- Yield Curve Vs. Fed Funds Rate
- U.S. Bond Yields
- Dividend Yield Vs. Bond Yield
- QE Vs. Bond Yields
- Money Supply
- Dow Theory
- Excess Reserves
- Central Bank Balance Sheets
- Fed Balance Sheet Vs. Dow Jones
- Credit Spread Vs S&P
- Total credit Vs. Dow Jones
- Debt
- Debt Vs. Delinquency
- % Debt Held by Foreigners
- Interest Payment on Government Debt
- Disposable Income Vs. Housing
- Retail Sales Vs. Disposable Income
- Tax Revenue Vs. Stocks
- Tax Revenue Vs. Savings Rate
- NIIP Vs. Currency
- Trade Balance Vs. Currency
- Deficit
- Deficit to Outlay Ratio
- China Power Consumption Vs. China GDP
- Freight Vs. GDP
- Inventory Vs. GDP
- PCE Vs. GDP
- GDP Vs. Trade Balance
- GDP Vs. 10 Year Bond Yield
- GDP Vs. PMI
- Profits Vs. Employment
- Employment-Population Ratio Vs. Wages
- Employment-Population Ratio Vs. GDP per Capita
- Unemployment Vs. GDP
- Part-time Employment
- Productivity Vs. CPI
- Output Gap Vs. CPI
- Taylor Rule Rate Vs. Gold
- PPI/CPI/PCE
- Retail Sales Vs. CPI
- 2 Year Vs. LIBOR/SOFR Vs. Fed Funds Rate
- Loan Growth Vs. Fed Funds Rate
- Fed Funds Rate Vs. CPI
- Fed Funds Rate Vs. Unemployment
- Delinquencies Vs. Unemployment
- Delinquency Vs. Fed Funds Rate
- Labor Force Vs. Unemployment
- Non-Farm Payrolls Vs. Unemployment
- Quits Rate Vs. Wage Inflation
- Wage Inflation Vs. Unemployment
- Wage Inflation Vs. CPI
- M2 Vs. CPI
- Capacity Utilization Vs. CPI
- Capacity Utilization Vs. Unemployment
- New Homes Vs. Rents
- Lumber Vs. Housing
- Savings Vs. Housing
- Housing Starts Vs. Unemployment
- Initial Jobless Claims Vs. S&P
- Consumer Sentiment Vs. S&P
- Durable Goods Orders Vs. S&P
- Building Permit Vs. Housing
- Construction Vs. Housing
- Adjustable Mortgage Vs. Fed Funds Rate
- Fixed Mortgage Rates Vs. 30 Year Bond Yield
- MZM Vs. 10 Year Bond Yield
- Gold Vs. 10 Year Bond Yield
- Dow/Gold Ratio
- GOFO Vs. Gold
- Gold/Silver COMEX
Posts tonen met het label Japan. Alle posts tonen
donderdag 24 november 2022
zaterdag 4 januari 2020
Stock Screener: Lukoil (LUKOY)
A major escalation happened in Iran and oil will be going higher. Russia will probably profit the most from this.
woensdag 11 december 2019
woensdag 3 januari 2018
Japan fiscal situation improves in 2018
The Ministry of Finance Japan has released a draft budget for 2018 and that report on the fiscal situation can be found here. I'll summarize my findings in this article.
Labels:
Japan
woensdag 4 januari 2017
Japan Fiscal Situation 2017
The Ministry of Finance Japan has released a draft budget for 2017 and that report on the fiscal situation can be
found here. I'll summarize my findings in this article.
Abstract:
The massive money printing from the Bank of Japan was started in 2013 and has continued ever since. It effectively increased tax revenues through a
higher stock market and deficits turned into surpluses. It did bring in a lower yield
environment to spur economic growth. The 10 year bond yield is kept at 0% through an unlimited buying program in November 2016 and interest payments have gone down because of that. But it also had adverse
consequences. The yen plunged ever since that November announcement and the Japan stock market didn't go up
significantly accounted for a weaker yen. When you take into account global bond yields are moving up, Japan could be getting into a lot of trouble if it wants to keep bond yields where they are.
maandag 19 september 2016
Japan Gold: The First Foreign Gold Miner in Japan
The recovery in the gold price has been driving investor interest into gold mining companies. In this article I'll introduce you to one country that has just started to open its doors to gold mining: Japan.
In 2012, the Mining Act of Japan was amended for the first time in 61 years. The Mining Amendment Act came into force on January 21, 2012.
Now there is one company that is leveraging on this new mining act and that's Japan Gold (TSX-V: JG) which started trading on 19 September 2016 on the TSX Venture Exchange.
To read more, go here.
In 2012, the Mining Act of Japan was amended for the first time in 61 years. The Mining Amendment Act came into force on January 21, 2012.
Now there is one company that is leveraging on this new mining act and that's Japan Gold (TSX-V: JG) which started trading on 19 September 2016 on the TSX Venture Exchange.
To read more, go here.
zondag 3 januari 2016
A Look At The Ministry of Finance Japan Draft 2016 Budget
One year has passed and Japan has not deteriorated as many analysts predicted. The Japanese stock market has gone up 10% since last year, the yen has been flat against the U.S. dollar, the Japanese housing market is rebounding, real GDP is at 1% and people who invested in the Japanese bond market didn't lose any of their money.
I mentioned in a previous post last year that Japan's situation wasn't that bad at all. The current account was improving, the budget deficit was contained, bond yields were falling and I said that the benefits of the restart of the nuclear reactors was going to boost the economy of Japan. Well, two of the 48 nuclear reactors have been restarted and many more are going to be restarted as approvals are underway. With this in mind, let's see how the fiscal situation will look like in 2016.
Go here for the analysis.
I mentioned in a previous post last year that Japan's situation wasn't that bad at all. The current account was improving, the budget deficit was contained, bond yields were falling and I said that the benefits of the restart of the nuclear reactors was going to boost the economy of Japan. Well, two of the 48 nuclear reactors have been restarted and many more are going to be restarted as approvals are underway. With this in mind, let's see how the fiscal situation will look like in 2016.
Go here for the analysis.
maandag 5 januari 2015
Ministry of Finance Japan Issues 2015 Budget: The Trend Is Actually Improving
Japan has been in the news a lot in 2014 because of its deteriorating fiscal situation. The Ministry of Finance Japan has approved the 2015 budget and a new report on the fiscal situation can be found here. I'll summarize my findings in this article.
First, let's focus on the trade and current account deficit in Japan. Both have been deteriorating rapidly in 2013, but since 2014 something has changed. The yen (FXY) has been plunging in 2014 (see chart below from Yahoo), just like it did in 2013 and that suggests that we would see large current account deficits and budget deficits going forward, but the opposite is happening.
The latest current account number in October 2014 was a surplus of 833.4 billion yen. The reason for this is because Japan's pension funds (which are the largest in the world with more than $1 trillion in assets) invested heavily in overseas stocks and they are planning to increase this exposure to 25% of their fund. As we all know, the U.S. stock market has been on a tear and Japan's current account has benefited from this (see chart below from tradingeconomics).
Exports are on the rise but haven't improved a lot if you account for a weaker yen (the yen plunged 20% in 2014 while exports rose only 10%). The trade balance is still negative, but somewhat improving because import costs for oil and gas have declined in 2014 (34% of total Japanese imports is energy). The latest November trade deficit figure came in at 891.9 billion yen (see chart below from tradingeconomics). This number is likely to improve as Japan's nuclear reactors are starting to come online in 2015.
To continue reading the analysis on budget and interest payments, go here.
First, let's focus on the trade and current account deficit in Japan. Both have been deteriorating rapidly in 2013, but since 2014 something has changed. The yen (FXY) has been plunging in 2014 (see chart below from Yahoo), just like it did in 2013 and that suggests that we would see large current account deficits and budget deficits going forward, but the opposite is happening.
The latest current account number in October 2014 was a surplus of 833.4 billion yen. The reason for this is because Japan's pension funds (which are the largest in the world with more than $1 trillion in assets) invested heavily in overseas stocks and they are planning to increase this exposure to 25% of their fund. As we all know, the U.S. stock market has been on a tear and Japan's current account has benefited from this (see chart below from tradingeconomics).
Exports are on the rise but haven't improved a lot if you account for a weaker yen (the yen plunged 20% in 2014 while exports rose only 10%). The trade balance is still negative, but somewhat improving because import costs for oil and gas have declined in 2014 (34% of total Japanese imports is energy). The latest November trade deficit figure came in at 891.9 billion yen (see chart below from tradingeconomics). This number is likely to improve as Japan's nuclear reactors are starting to come online in 2015.
To continue reading the analysis on budget and interest payments, go here.
donderdag 20 november 2014
Decoupling Japan Vs. gold/stocks
On 9 November I started to write about the Japan carry trade versus gold.
Exactly at that moment, gold and the Japanese yen carry trade decoupled. Also stocks decoupled from the Japanese yen carry trade. Maybe they know we know and need to find something else to manipulate the markets.
Or we could be starting the hyperinflationary phase where the yen plunges and stocks don't go up anymore, while gold does go up.
Exactly at that moment, gold and the Japanese yen carry trade decoupled. Also stocks decoupled from the Japanese yen carry trade. Maybe they know we know and need to find something else to manipulate the markets.
Or we could be starting the hyperinflationary phase where the yen plunges and stocks don't go up anymore, while gold does go up.
donderdag 6 november 2014
Correlation: Will Japan be able to keep gold steady in JPY in 2015?
Japan has upped the speed of money printing starting in 2013, just at the same time the U.S. did QE3. This has actually been keeping the USD and JPY exchange rate stable. But now when Japan announced QE infinity with triple the size of U.S. QE compared to their GDP, that stable exchange rate will start to deteriorate. Be aware that one must not look at the absolute size of QE, but needs to look at QE as a percentage of GDP. When a low GDP country prints the same amount of money as a large GDP country, its currency will depreciate much faster than the currency of the larger GDP country.
Another pretty stable exchange rate was gold compared to JPY. Since 2013 the gold price hasn't done anything against the JPY. This means all of the printed money went into Japanese stocks instead of gold. I think the central banks have perfectly orchestrated it.
But what will happen when we have this regime change now? I think the gold price will definitively increase in Japanese JPY, that will be inevitable with this size of QE.
It will be interesting to watch what the U.S. will do next when they see all this deflation coming their way.
What's even more interesting is that the Japan yen carry trade is so obvious now.
They borrow yen to use those yen to buy equities and short gold. The graph above shows this correlation between USD/JPY and gold, which I will add to our list of correlations. I suspect Japan wants to hold gold steady to show all is well and that there is no inflation. This carry trade cannot keep going on forever as it will blow up at some point. Physical supply and demand will eventually be the most logical conclusion. And the yen carry trade will only end when borrowing costs start to rise due to an increase in interest rates. So watch out for the rise in yields, which will prick the carry trade bubble. Another scenario could be that the Japanese debt is so unsustainable that we get a Greece situation where bond yields start to spike. And finally the ultimate scenario will be that the yield on the carry traded yen equals the yield on the U.S dollar, that's the scenario where carry trading doesn't work anymore as you need to have a difference in yield between the two currencies. We are already seeing this has happened in Germany, where yields are the same as in Japan. Which means no carry trade is possible for euro yen based on yield spread. And I'm pretty sure U.S. bond yields will be coming down as GDP growth slows down, so U.S. bond yields will be converging to Japanese bond yields as well, and that will be the end of it.
Another pretty stable exchange rate was gold compared to JPY. Since 2013 the gold price hasn't done anything against the JPY. This means all of the printed money went into Japanese stocks instead of gold. I think the central banks have perfectly orchestrated it.
But what will happen when we have this regime change now? I think the gold price will definitively increase in Japanese JPY, that will be inevitable with this size of QE.
It will be interesting to watch what the U.S. will do next when they see all this deflation coming their way.
What's even more interesting is that the Japan yen carry trade is so obvious now.
Labels:
correlation,
Gold,
Japan,
QE
dinsdag 15 juli 2014
Waiting for the Plunge in Stock Markets
This is not going to end well I tell you. We are significantly overvalued at 123%. The question is: "When will it happen?"
I think it happens soon, because when we look at Japan, the GDP estimates there are now in negative territory. Japan second quarter GDP is forecasted to drop 10% year over year. That means the Nikkei will surely plummet and don't even think this won't affect the U.S. markets.
| Japan GDP |
vrijdag 11 april 2014
Japanese stock market breaks below support
As I predicted a month ago, the Japanese stock market has started to break down below support. Especially when they refrain from adding stimulus. We also know that the sales tax is hitting the Japanese consumer and that will worsen the downtrend.
maandag 17 maart 2014
Japan's stock market is about to crash
If you want ideas which investment to make in the coming months, I would expect a decline in the Japanese stock market.
First, we note that the 10 year Japanese bond yield at 0.6% is pretty competitive against the dividend yields of Japanese stocks at 1.8% (Chart 1). So stocks aren't such good value anymore compared to a year ago when dividend yields were at 2.8% compared to a 10 year treasury yield of 0.7%. Moreover, the P/E ratio of Japanese stocks is currently at 13, which isn't particularly cheap.
Secondly, I have written extensively about the dire fiscal situation in Japan. Japan has a current account deficit, is printing money to stimulate their economy and more and more of its interest payments on Japanese debt is financed by less tax revenue. Obviously, this won't be bullish for Japanese stocks.
But most importantly, recent numbers on the consumer confidence in Japan, point to a decline in the stock market for the coming months.
Read on here.
First, we note that the 10 year Japanese bond yield at 0.6% is pretty competitive against the dividend yields of Japanese stocks at 1.8% (Chart 1). So stocks aren't such good value anymore compared to a year ago when dividend yields were at 2.8% compared to a 10 year treasury yield of 0.7%. Moreover, the P/E ratio of Japanese stocks is currently at 13, which isn't particularly cheap.
| Chart 1: Japan: Dividend yield Vs. Treasury Yield |
Secondly, I have written extensively about the dire fiscal situation in Japan. Japan has a current account deficit, is printing money to stimulate their economy and more and more of its interest payments on Japanese debt is financed by less tax revenue. Obviously, this won't be bullish for Japanese stocks.
But most importantly, recent numbers on the consumer confidence in Japan, point to a decline in the stock market for the coming months.
Read on here.
Labels:
confidence,
consumer,
Japan,
Nikkei
donderdag 6 februari 2014
Japan Carry Trade
When you know your country (in this case Japan) is printing massive amounts of money and is debasing its currency, you can profit from this. You just borrow the debasing currency (yen) at ultra low yields and with that money you buy high yielding assets like the S&P500 or high yielding bonds in other countries.
So if the yen for example declines against the U.S. dollar (blue graph goes up), then you buy the S&P500 (red graph goes up). It also goes the other way round. When the yen starts increasing in value, people are going back into the yen to repay the borrowed currency by selling their high yielding assets.
Another example of carry trade is the U.S. debasing its currency with QE while emerging markets profit from this money printing. This carry trade is now unwinding as currency is flowing out of the emerging market currencies.
The key is: monitoring the USD/JPY exchange rate.
Labels:
carry,
correlation,
Japan,
trade
woensdag 15 januari 2014
Buying Japan is Picking Flowers in Front of an Incoming Train
Japan is undergoing a lot of changes today and one of the most important changes to investors is their fiscal situation. In a previous post almost a year ago, I analyzed the dismal fiscal situation in Japan, pointing out how their budget deficits and debt burdens are growing. I want to make an update on that as investors are focusing more and more on Japan these days.
The Ministry of Finance Japan has issued a new report on the fiscal situation which can be found here. This report is dated from December 2013.
Let's first focus on the trade and current account deficit in Japan. Both have been deteriorating rapidly in 2013. In fact, we are hitting new lows as we speak. The primary reason is that the yen has devalued a lot since 2013. As I noted earlier in other posts, the currency valuation is correlated to the deficit. If the valuation of the currency of a country goes down, that means that they will need to import products at a higher price and they will export products at a lower price. This naturally leads to a higher deficit. Evidence can be found in the soaring costs for importing oil to Japan. Oil imports basically almost doubled in price as noted in this article.
If we then move on to the budget deficits, there is a bit of light at the end of the tunnel. The deficit to outlay ratio (which gives the likelihood for hyperinflation) has come down from a peak of 62% to 48% which is an improvement, but we are still in hyperinflationary territory (ratio above 40% is hyperinflationary).
Chart 3 illustrates that the government has cut back on spending (red chart) and the budget deficits have come down (green chart). It also shows how tax revenues in Japan (blue chart) have gone up due to a rising Japanese stock market. This rise in tax revenues has decreased the budget deficits in Japan.
Now we come to the most interesting part of this analysis: the interest payments on government debt. To find out about this, go here.
The Ministry of Finance Japan has issued a new report on the fiscal situation which can be found here. This report is dated from December 2013.
Let's first focus on the trade and current account deficit in Japan. Both have been deteriorating rapidly in 2013. In fact, we are hitting new lows as we speak. The primary reason is that the yen has devalued a lot since 2013. As I noted earlier in other posts, the currency valuation is correlated to the deficit. If the valuation of the currency of a country goes down, that means that they will need to import products at a higher price and they will export products at a lower price. This naturally leads to a higher deficit. Evidence can be found in the soaring costs for importing oil to Japan. Oil imports basically almost doubled in price as noted in this article.
![]() |
| Chart 1: Japan Current Account and Trade Balance |
| Chart 2: Deficit to Outlay Ratio Japan |
| Chart 3: Japan: Tax Revenue, Expenditures, Budget Deficit |
vrijdag 27 december 2013
Euro surges against U.S. Dollar and Japanese Yen
As I predicted here and here, both the U.S. dollar and the Japanese yen are underperforming the euro. This is mainly because the central bank balance sheets of the U.S. and Japan are inflating, while the balance sheet of the Eurozone is shrinking/flatlined.
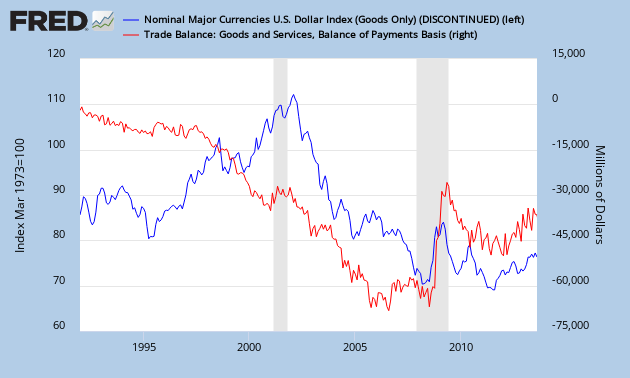
Moreover, we see that the Eurozone has a trade surplus while the U.S. and Japan have a trade deficit, which according to this correlation below, is good for the euro and bad for the U.S. dollar and Japanese yen.
At this moment, if all things stay equal, the euro will continue its rise against the U.S. dollar and Japanese yen. An extra catalyst following the asset-quality review (AQR) is that the European banks need to increase capital next year and they will need to buy euros for that.
This also means that U.S. and Japanese bonds will continue their decline as following correlation between currency and bond yields suggests.
You see, this is the power of correlations... Maybe I should rename this blog to: "Correlation Economics".
![]() |
| Central Bank Balance Sheet Expansion is Bad for the Currency |
Moreover, we see that the Eurozone has a trade surplus while the U.S. and Japan have a trade deficit, which according to this correlation below, is good for the euro and bad for the U.S. dollar and Japanese yen.
![]() |
| Deficit is correlated to Currency Valuation |
This also means that U.S. and Japanese bonds will continue their decline as following correlation between currency and bond yields suggests.
You see, this is the power of correlations... Maybe I should rename this blog to: "Correlation Economics".
dinsdag 4 juni 2013
When will inflation in Japan show up?
People are wondering if the money printing experiment in Japan is actually going to be inflationary or not. As we all know, the inflation rate is measured by the CPI (consumer price index). If the CPI goes up, we have inflation.
First, let's look at food prices. Zero Hedge reports that McDonald's has hiked the price of a burger in Japan by 20%. If we consider this price hike as a proxy for the overall food price in Japan, we could see a significant increase in the CPI coming.
Second, we take a look at the Japanese housing market. The Japanese housing market has always been in a decline for the last 15 years, but now we see signs of stabilization. Housing prices are about to rise in the coming years. In the metropolitan areas for example, we have seen land prices go up at an annual rate of 11.5% in 2012.
Third, fuel and energy costs are going through the roof. With the Fukushima disaster, a part of the nuclear energy had to be diverted to fuel. In fact, LNG imports soared to 86.9 million tonnes. Added to this disaster, the yen weakened considerably in 2013 which led to rising fuel and energy costs. We can witness this in the rising LNG prices in Japan. These events are a very good example of why a weaker yen is not a good thing, instead it creates an environment where people's purchasing power declines. In this case the price of the imports of fuel are going up and this will add to the trade deficit of the country. The statistics bureau of Japan recently put out the latest numbers on the CPI. Fuel was contributing the most to the rising costs of living.
So basically, we see that the 3 biggest components of the CPI are going up in Japan. It would surprise me if the CPI would decline in the coming months.
Continue reading here.
The CPI of Japan consists of the items given in Chart 1. The items with the most weight in it are food, housing, transportation and fuel. Therefore, it is important to watch food and energy costs as well as housing prices in Japan.
| Chart 1: Items in CPI of Japan (2010) |
Second, we take a look at the Japanese housing market. The Japanese housing market has always been in a decline for the last 15 years, but now we see signs of stabilization. Housing prices are about to rise in the coming years. In the metropolitan areas for example, we have seen land prices go up at an annual rate of 11.5% in 2012.
Third, fuel and energy costs are going through the roof. With the Fukushima disaster, a part of the nuclear energy had to be diverted to fuel. In fact, LNG imports soared to 86.9 million tonnes. Added to this disaster, the yen weakened considerably in 2013 which led to rising fuel and energy costs. We can witness this in the rising LNG prices in Japan. These events are a very good example of why a weaker yen is not a good thing, instead it creates an environment where people's purchasing power declines. In this case the price of the imports of fuel are going up and this will add to the trade deficit of the country. The statistics bureau of Japan recently put out the latest numbers on the CPI. Fuel was contributing the most to the rising costs of living.
| Table 1: Consumer Prices: Change from the Previous Year in 2012 |
Continue reading here.
donderdag 9 mei 2013
Central Bank Balance Sheets: U.S., Eurozone, Japan
This page is created to monitor the balance sheet of the U.S., Eurozone, Japan and the United Kingdom.
There is a strong correlation between the price of gold and the expansion of the total sum of all central bank balance sheets in the world.
ECB = blue
U.S. Federal Reserve = red
Bank of Japan = green
Bank of England = orange
(The Chinese balance sheet is not included in this graph as it is not available on FRED)
source: tradingeconomics.com
The U.S. balance sheet consists of Treasuries and Mortgage backed securities.
The Treasury General Account provides cash for Bank Reserve Balances (which are a cost if they go up too much). Because the TGA is a liability—a source of funding for the Fed—when it falls, reserve balances must go up by a corresponding amount.
Bank reserves cannot go below a certain level.
The Federal Reserve Balance Sheet is connected to the following entities.
If you want to follow up on the Repo Madness. This FRED link will give you the amount of Repo's they buy. Usually, the amount of repos bought will increase when the commercial paper market gets spooked.
Watch the overnight reverse repo (RRP). If this skyrockets, there will be downward pressure on the USD.
zondag 21 april 2013
Why you shouldn't buy Japanese equities
This is why you shouldn't buy Japanese stocks to profit on it as an American citizen. As the Nikkei goes up, so does the Yen decline against the USD.
So your profit is zero.
maandag 8 april 2013
Japan got its inflation going
Japan got its inflation allright, USD/JPY just went to 100 and I see 200 coming soon.
Abonneren op:
Posts (Atom)