- List of Correlations
- Gold Checklist
- Copper Checklist
- Gold Forecaster
- Oil Forecaster
- Stock Forecaster
- Bond Forecaster
- USD Forecaster
- Poo Forecaster
- Bitcoin Checklist
- Q Ratio
- Stock Valuation
- Leading/Coincident Indicator
- Misery Index
- Junk Bonds Vs. Stocks
- Currency Vs. Bonds
- Yield Curve Vs. Fed Funds Rate
- U.S. Bond Yields
- Dividend Yield Vs. Bond Yield
- QE Vs. Bond Yields
- Money Supply
- Dow Theory
- Excess Reserves
- Central Bank Balance Sheets
- Fed Balance Sheet Vs. Dow Jones
- Credit Spread Vs S&P
- Total credit Vs. Dow Jones
- Debt
- Debt Vs. Delinquency
- % Debt Held by Foreigners
- Interest Payment on Government Debt
- Disposable Income Vs. Housing
- Retail Sales Vs. Disposable Income
- Tax Revenue Vs. Stocks
- Tax Revenue Vs. Savings Rate
- NIIP Vs. Currency
- Trade Balance Vs. Currency
- Deficit
- Deficit to Outlay Ratio
- China Power Consumption Vs. China GDP
- Freight Vs. GDP
- Inventory Vs. GDP
- PCE Vs. GDP
- GDP Vs. Trade Balance
- GDP Vs. 10 Year Bond Yield
- GDP Vs. PMI
- Profits Vs. Employment
- Employment-Population Ratio Vs. Wages
- Employment-Population Ratio Vs. GDP per Capita
- Unemployment Vs. GDP
- Part-time Employment
- Productivity Vs. CPI
- Output Gap Vs. CPI
- Taylor Rule Rate Vs. Gold
- PPI/CPI/PCE
- Retail Sales Vs. CPI
- 2 Year Vs. LIBOR/SOFR Vs. Fed Funds Rate
- Loan Growth Vs. Fed Funds Rate
- Fed Funds Rate Vs. CPI
- Fed Funds Rate Vs. Unemployment
- Delinquencies Vs. Unemployment
- Delinquency Vs. Fed Funds Rate
- Labor Force Vs. Unemployment
- Non-Farm Payrolls Vs. Unemployment
- Quits Rate Vs. Wage Inflation
- Wage Inflation Vs. Unemployment
- Wage Inflation Vs. CPI
- M2 Vs. CPI
- Capacity Utilization Vs. CPI
- Capacity Utilization Vs. Unemployment
- New Homes Vs. Rents
- Lumber Vs. Housing
- Savings Vs. Housing
- Housing Starts Vs. Unemployment
- Initial Jobless Claims Vs. S&P
- Consumer Sentiment Vs. S&P
- Durable Goods Orders Vs. S&P
- Building Permit Vs. Housing
- Construction Vs. Housing
- Adjustable Mortgage Vs. Fed Funds Rate
- Fixed Mortgage Rates Vs. 30 Year Bond Yield
- MZM Vs. 10 Year Bond Yield
- Gold Vs. 10 Year Bond Yield
- Dow/Gold Ratio
- GOFO Vs. Gold
- Gold/Silver COMEX
Posts tonen met het label backwardation. Alle posts tonen
dinsdag 10 januari 2023
zondag 4 september 2022
Oil Forward Curve Is Useless
Labels:
backwardation,
curve,
forward,
oil
maandag 22 juni 2020
Backwardation in Gold: GOFO = LIBOR - GLR
Gold Forward Rate GOFO = LIBOR - Gold Lease Rate GLR.
This is stated as a percentage, and is almost always positive, meaning the gold price for future delivery of gold is higher than the current spot price. If the GOFO is negative, this means that it is cheaper to borrow against gold than dollars, and is very unusual. Generally speaking, it should be cheaper to borrow dollars for just dollars, without involving another commodity, however the GOFO has turned negative on several occasions in the past due to periods of high physical demand.
So what is the status today?
Gold Lease Rates are negative -2% and we even had spikes to -4%.
LIBOR rates are close to zero. 3 month LIBOR is at 0.3%.
That makes GOFO = 0.3% - (-2%) = 2.3%
GOFO is now almost in backwardation and that should tell us that there is a looming physical shortage.
This is stated as a percentage, and is almost always positive, meaning the gold price for future delivery of gold is higher than the current spot price. If the GOFO is negative, this means that it is cheaper to borrow against gold than dollars, and is very unusual. Generally speaking, it should be cheaper to borrow dollars for just dollars, without involving another commodity, however the GOFO has turned negative on several occasions in the past due to periods of high physical demand.
So what is the status today?
Gold Lease Rates are negative -2% and we even had spikes to -4%.
LIBOR rates are close to zero. 3 month LIBOR is at 0.3%.
That makes GOFO = 0.3% - (-2%) = 2.3%
GOFO is now almost in backwardation and that should tell us that there is a looming physical shortage.
zaterdag 25 april 2015
Oil going back into backwardation soon
Oil is going back into backwardation as predicted and this results in higher oil prices.
Labels:
backwardation,
Contango,
oil
vrijdag 23 mei 2014
LME copper stock hits multi-year low
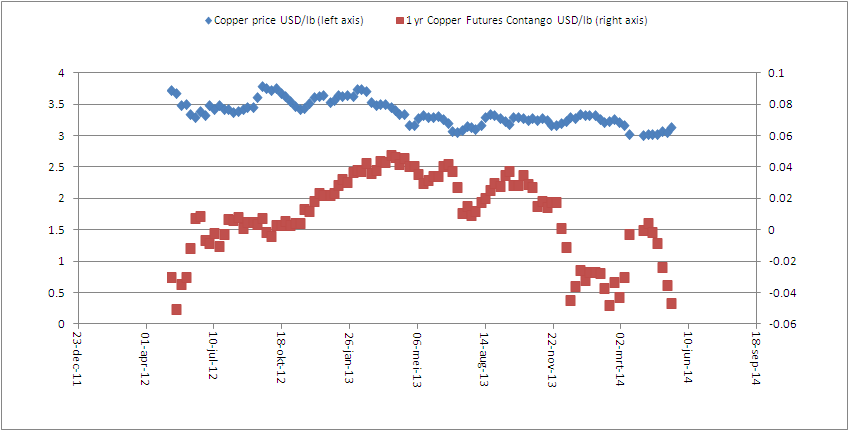
The latest numbers on the forward curve for copper show something interesting. Copper went from contango steeply into backwardation again in just a month (see chart below, created by Correlation Economics). This indicates price strength in copper.
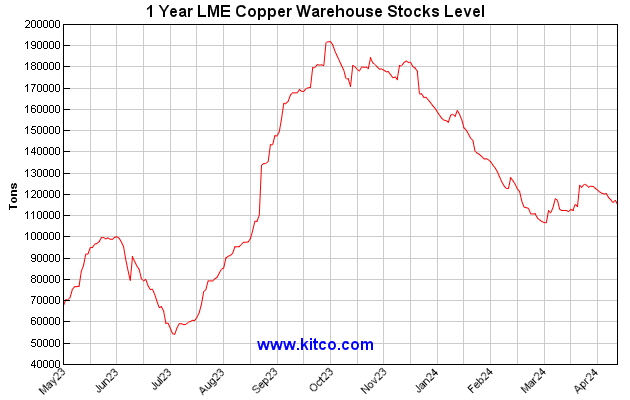
And consistent with our correlation between copper backwardation and LME stock levels, the LME stock level went down as well, hitting multi-year lows. We are hitting below the 200000 tonne level, never seen since 2008.
This indicates to me that there is a tight supply of copper. We may have a surplus in copper concentrate, but what is off the radar is the deficit in global refined copper. That deficit stands at approximately 600000 tonne this year. If this trend of backwardation widens in the coming months when LME stock levels hit critical low levels, copper could rise some more in price.
To read further, go here.
And consistent with our correlation between copper backwardation and LME stock levels, the LME stock level went down as well, hitting multi-year lows. We are hitting below the 200000 tonne level, never seen since 2008.
This indicates to me that there is a tight supply of copper. We may have a surplus in copper concentrate, but what is off the radar is the deficit in global refined copper. That deficit stands at approximately 600000 tonne this year. If this trend of backwardation widens in the coming months when LME stock levels hit critical low levels, copper could rise some more in price.
To read further, go here.
Labels:
backwardation,
China,
copper,
LME,
stock
dinsdag 10 december 2013
Copper Turns to Backwardation
We finally went into backwardation in full force on copper the previous week, so I expect rising copper prices soon.
Copper miners are also bottoming out, take a look at Freeport-McMoRan and Capstone Mining.
Labels:
backwardation,
copper
dinsdag 19 november 2013
What do new rules at LME mean for metal prices?
Weeble posted an interesting question, which I don't know the answer to, but I can guess:
So basically the LME shortens the warehousing queues by decreasing waiting time duration to 100 days (July 2013) and now to 50 days (November 2013). Beginning from April next year.
I'm not an expert on LME warehousing. But what I've read is that traders think it will make prices of commodities go down, because all that supply goes into the market and it would become less attractive for warehousing companies to bid for metal. On the other hand, this change in plans means lower warehouse levels and that will make delivery more difficult. There will be delays. What if there is a sudden demand in copper in China while warehouse levels are lower and what if dealers need to deliver on the expiring short positions. We will see backwardation. As a matter of fact, backwardation is correlated with LME copper levels as shown below.
You can see that LME copper levels go up and down (Chart 1) in striking similarity with the copper contango curve (Chart 2: red graph). It's too early to make conclusions though...
And as you know from the copper contango theory, if copper goes into backwardation, the copper price will go up. So a lower LME warehouse level due to the new rules at the LME, will result in higher copper prices. That's my guess.
Remember what we had in the nickel market. We almost had a nickel default at the LME in 2006.
And what happened when nickel was at record low stock levels? The nickel price soared afterwards.
Everything points to higher prices in my opinion.
Albert, I always find your blog very educational.
I am interested in what you think of the following. It seems to me to be a big deal but nobody is commenting on it. Will it cause more bullion to come in to the market short term or will the increase in transparency show the weakness in the system? Thanks.
http://uk.reuters.com/article/2013/11/07/uk-lme-warehouses-idUKBRE9A611O20131107
So basically the LME shortens the warehousing queues by decreasing waiting time duration to 100 days (July 2013) and now to 50 days (November 2013). Beginning from April next year.
I'm not an expert on LME warehousing. But what I've read is that traders think it will make prices of commodities go down, because all that supply goes into the market and it would become less attractive for warehousing companies to bid for metal. On the other hand, this change in plans means lower warehouse levels and that will make delivery more difficult. There will be delays. What if there is a sudden demand in copper in China while warehouse levels are lower and what if dealers need to deliver on the expiring short positions. We will see backwardation. As a matter of fact, backwardation is correlated with LME copper levels as shown below.
You can see that LME copper levels go up and down (Chart 1) in striking similarity with the copper contango curve (Chart 2: red graph). It's too early to make conclusions though...
| Chart 1: Copper Warehouse Stocks Level |
| Chart 2: Copper Contango Theory |
Remember what we had in the nickel market. We almost had a nickel default at the LME in 2006.
Excerpts from the LME’s press release of August 16, 2006:
Those with short positions in nickel falling prompt on Friday 18 August 2006, and on subsequent prompt dates until further notice, who are unable to effect physical delivery an/or unable to borrow metal at a backwardation of no more than $300.00 per tonne per day, shall be able to defer delivery for a day at a penalty of $300.00 per tonne. Those with long positions for prompt on those days who are subject to deferred delivery shall be entitled to compensation of $300.00 per tonne per day
And what happened when nickel was at record low stock levels? The nickel price soared afterwards.
| Chart 3: Nickel stock levels Vs. Nickel Price |
Labels:
backwardation,
copper,
correlation,
default,
LME,
metal,
nickel,
prices,
stock
vrijdag 2 augustus 2013
Gold Backwardation Explained By James Turk
If you want to know what gold backwardation means, read this article of James Turk. Very interesting.
Let's say we have two currencies A (euro) and B (USD). Then the following is true:
- A's interest rate < B's interest rate
- A is in contango against B
- A's value rises going into the future
- Higher interest rates means a higher risk of debasement of the currency.
Now let's look at two other currencies A (USD) and B (gold):
- USD's interest rate < gold's interest rate (lease rate)
- USD is in contango against gold (or gold is in backwardation)
- USD's value rises going into the future (or gold's value declines going into the future = negative GOFO)
- Higher interest rates means a higher risk of debasement of the currency.
Now gold's interest rate is higher than the USD's interest rate. Which means gold has a higher risk of debasement than the USD. This is virtually impossible because gold cannot be debased.
Which means something has to give. This is a rare event and will mark a bottom in the gold price.
Let's say we have two currencies A (euro) and B (USD). Then the following is true:
- A's interest rate < B's interest rate
- A is in contango against B
- A's value rises going into the future
- Higher interest rates means a higher risk of debasement of the currency.
Now let's look at two other currencies A (USD) and B (gold):
- USD's interest rate < gold's interest rate (lease rate)
- USD is in contango against gold (or gold is in backwardation)
- USD's value rises going into the future (or gold's value declines going into the future = negative GOFO)
- Higher interest rates means a higher risk of debasement of the currency.
Now gold's interest rate is higher than the USD's interest rate. Which means gold has a higher risk of debasement than the USD. This is virtually impossible because gold cannot be debased.
Which means something has to give. This is a rare event and will mark a bottom in the gold price.
Labels:
backwardation,
GOFO,
Gold,
James,
Turk
donderdag 27 september 2012
Copper turns back to backwardation
It seems that copper is going back into backwardation, so that's good for equities, oil and commodities.
| Chart 1: Copper Contango |
Labels:
backwardation,
Contango,
copper
dinsdag 17 juli 2012
Copper turns back to Backwardation
It seems that the red graph is going down, which means it is likely that copper goes into backwardation again. So the copper price should rise if all goes well, together with the S&P.
| Chart 1: Copper Contango |
Labels:
backwardation,
Contango,
copper
zaterdag 7 juli 2012
Copper Price VS. Contango Report
I decided to start monitoring the contango-backwardation curve of copper (Chart 1). In a previous article I noted a pretty significant correlation between contango and price of copper.
We see that the negative correlation between copper price and 1 yr futures contango is still existing. But it's difficult to predict the price of copper, because the contango curve and the price curve are almost exactly following each other. We could say we almost have a 100% correlation here.
But, something weird happened on 14 May 2012 though, where the copper price was in steep backwardation, but the copper price didn't go up... So there still are discrepancies in this correlation.
Labels:
backwardation,
Contango,
copper,
Price,
report
vrijdag 22 juni 2012
Copper Turns Back to Contango: Bearish for Copper Price
In a previous article I pointed out how copper contango/backwardation correlates with the copper price. Since June 11th 2012, copper went back into contango which isn't boding well for copper prices (Chart 1). The China PMI is also going down lately, which means demand for commodities from China will be sluggish.
Labels:
backwardation,
Contango,
copper,
Price
zondag 6 mei 2012
Copper turns to backwardation, prices poised to rise
I have been monitoring the copper warehouse stock levels in previous articles and today I came across an interesting article on Seekingalpha talking about copper futures contango. In that article the author gave a historical chart of the premium or discount for contracts extending about a year to 18 months in the future.
We will see that backwardation will have a positive effect on copper prices and much more. The Chinese have been doing very odd things with their copper warehouse stocks.
To read about this go to: Copper turns to backwardation.
Labels:
backwardation,
China,
copper,
LME
Abonneren op:
Posts (Atom)